11 When Price Competition Destroys Profit
Rivalry turns your profit curve into a surface, and in the worst case it flattens
Everything so far has treated profit as something you build out of three ingredients you control and one you have to learn. You set the price, you choose the cost structure, you commit the fixed costs, and demand is the unknown you go and estimate.
That framing has carried the whole book, and it holds only while nobody else is selling.
Add a rival and something changes that no amount of better estimation fixes. The rival is not another source of noise in your demand curve. The rival is choosing a price, on purpose, in response to yours, and revising it when you revise yours. You are no longer solving a problem. You are in an argument with someone who is solving the same problem from the other side.
Profit Becomes a Surface
The last chapter read profit as a curve, and the curve was a picture of this:
\[ \mathsf{\pi(p) = (p - c)\,q(p) - f} \]
One price in, one profit out, with your demand curve supplying the quantity. Under rivalry that function takes a second argument:
\[ \mathsf{\pi_i(p_i, p_j)} \]
Subscripts — \(\mathsf{i}\) means you and \(\mathsf{j}\) means the other firm, so \(\mathsf{p_i}\) is your price and \(\mathsf{p_j}\) is theirs. Nothing is squared or multiplied; the small letter is only a name tag. \(\mathsf{\pi_i(p_i, p_j)}\) reads “your profit depends on both prices.”
Your profit now depends on your price and your rival’s. Nothing about the logic changed and everything about the geometry did. Your demand is no longer a curve you estimated once; it sits somewhere different depending on what the other firm charges. If they cut price, yours shifts in. If they raise it, yours shifts out. If they enter a segment you thought was yours, it splits.
So the profit curve you learned to read is one slice through something larger. Fill in a slice for every price the rival might charge and the slices become a surface.
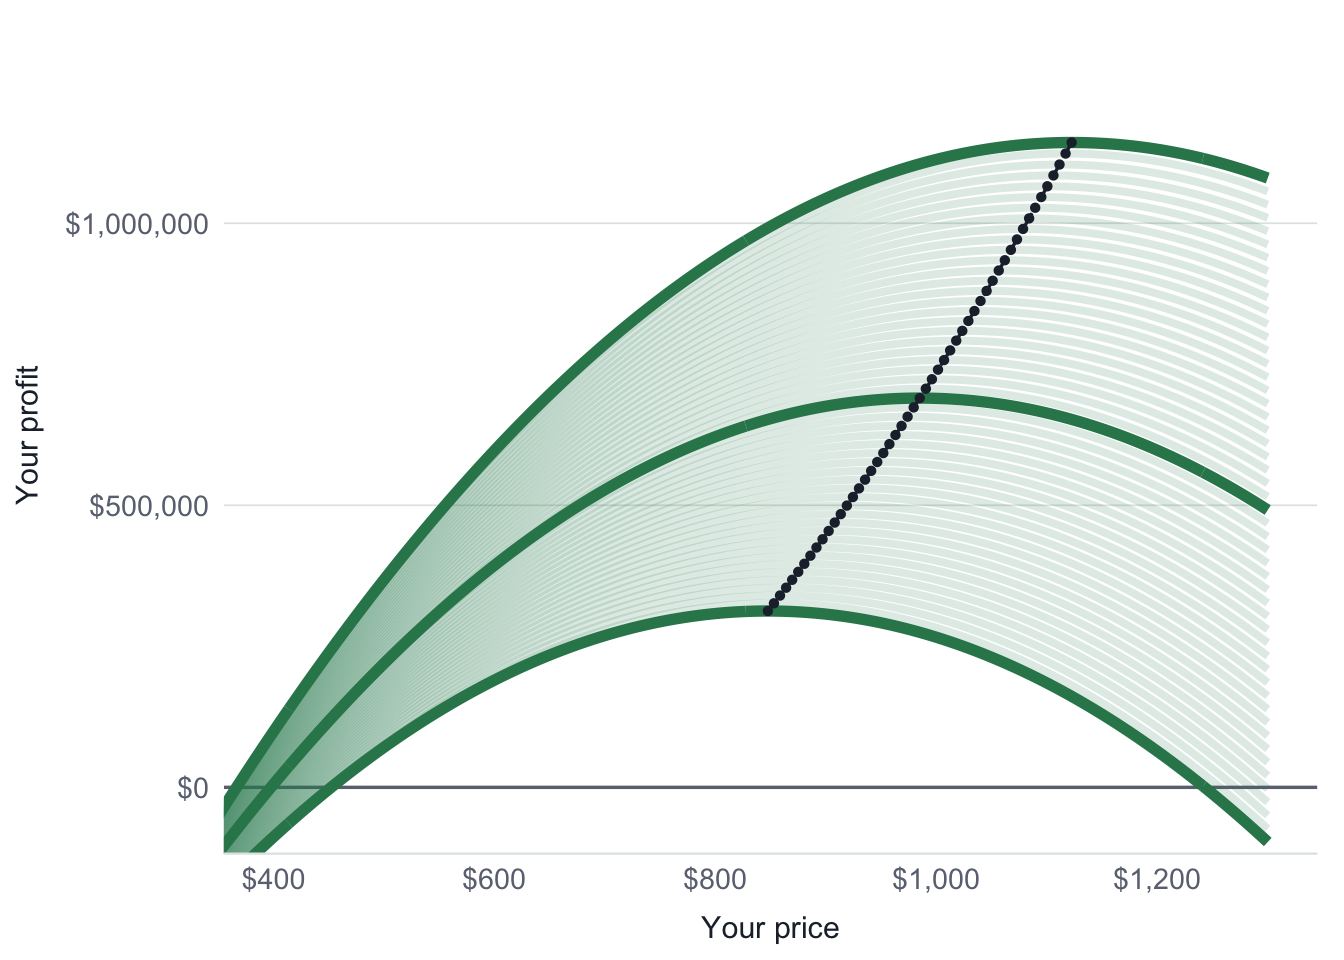
The line of dots along the ridge is worth noticing now, because the next chapter is entirely about it. It is your best price as a function of theirs, and it says that under rivalry you no longer have a best price. You have a rule for finding one once you know what they are doing.
Move the rival yourself and watch what it does to you.
The solid gray curve is where you were when the rival charged $800; the dashed gray line is the ridge, the path the peak travels. Push the rival down toward $300 and your whole curve sinks while your best price retreats with it — you are not being outsold, you are being compressed. Push them up toward $1,300 and you follow them up, earning more at a higher price without doing anything differently.
That dashed ridge is a straight line, and it is worth knowing why before the next chapter derives it. Every dollar the rival adds sends some customers your way, which lifts your demand, which makes a slightly higher price your best answer. With demand this shape the relationship comes out exactly linear: your best price is a fixed starting point plus a little over a quarter of whatever they charge. You follow them, and you follow them partway.
Say that last part carefully, because it is the hinge of the next two chapters. You match a fraction of their move rather than all of it, and so do they. Neither firm chases the other to the bottom, and neither escapes upward alone. Two partial responses pointing at each other is what settles rivalry at a price, and it is why the identical-goods case that follows is so brutal: strip the differentiation out and that fraction goes to one.
The Mistake Almost Everyone Makes
Here is how the reasoning usually goes wrong, and it goes wrong at the last step rather than the first.
A founder estimates willingness to pay honestly. They pick a price the evidence supports, work out the contribution, check that the volume covers the commitments, and conclude the venture is worth doing. Every step is sound. Then they act on a number computed at the price they would like to charge, rather than at the price that survives once somebody else is choosing too.
Look back at the surface. The tallest curve on it is real, and it is what you get when the rival prices at $1,300 — a choice they made for their own reasons and can unmake on a Tuesday. Building on that peak means building on someone else’s decision.
None of that is hard to compute once it is specified, and the specifying is the part that is yours. Which firm is actually your rival, what a customer would call the same thing, and whether the two of you are selling into one market or two that happen to overlap — those decide what the arithmetic is about, and getting any of them wrong produces an answer that is precise and about somebody else’s business.
The question that replaces what is my optimal price? is harder and more useful:
What price survives when the other firm is optimizing too?
Everything you learned still applies. Contribution, fixed-cost commitment, required penetration, sensitivity — all of it holds. The change is where you evaluate them. A venture that is feasible in isolation can be infeasible under rivalry, and a structure that looked robust can turn fragile the moment margins compress.
The Unforgiving Case
To see how far this can go, take rivalry in its harshest form.
Two firms. Identical products. Customers who care about nothing but price, with no brand preference, no switching cost, and no reason to prefer one seller over the other. In that world even a one-dollar gap moves the entire market.
Suppose your costs match your rival’s, and they are charging $100. You can take every customer by charging $99, so you do. They can take them all back at $98, so they do. Each move is individually rational and each invites the next.
The undercutting stops at one place. When price reaches variable cost, the next cut loses money on every unit sold, and neither firm has a profitable move left:1
\[\mathsf{P = c}\]
Nothing about that outcome required cooperation, collusion, or a truce. It is simply where the logic runs out. And at that price, contribution is gone, so profit is:
\[\mathsf{\pi = (P - c)Q - f = -f}\]
You sell the entire time and never recover a dollar of what you committed.
Zero Profit Does Not Mean Zero Income
That result confuses people, and the confusion is worth clearing up because it is the reason the pattern keeps catching founders who are paying attention.
Economic profit of zero does not mean nothing lands in your pocket. A firm pricing at cost can still generate accounting income, pay a salary, run cash through the business, and look busy and even successful from outside. What it cannot do is earn a return above what the same capital, time, and risk would have earned somewhere else.
Economic profit — what is left after the return you could have earned elsewhere with the same capital, time and risk. Accounting income can be healthy while this is zero.
So the honest description of a mature undifferentiated market is that people work hard, take real risk, collect real income, and earn nothing for the risk. Which is exactly the shape of the most common story in entrepreneurship.
Someone says I am making a hundred thousand dollars a year from my drop-shipping store.
Before asking anything clever about that sentence, ask the plain question: a hundred thousand dollars of what? Very often the answer is revenue. Money arrived; nothing has been subtracted. The cost of the goods, the advertising that produced the orders, the returns, the platform’s cut, and the hours are all still to come out, and what remains may be a fraction of the number or none of it.
This is not a beginner’s mistake, which is what makes it worth naming. Founders quote revenue, press coverage reports revenue, pitch decks lead with revenue, and investors who know better let it stand because it is the number that grows fastest and photographs best. An entire culture has settled on describing success with the one figure that says nothing about whether the business works.
So take the sentence at its most generous and assume they meant profit. Even then the questions that decide whether it is a business are all about what happens next. What if another seller sources the same product a little cheaper? What if six more enter? What if advertising costs rise, or the platform starts sorting by price?
If the product is undifferentiated and entry is easy, the income is real and the profit is borrowed. What looked like a business may have been a temporary gap in competition.
The Pattern Repeats
This is not a thought experiment. It has run in industries as far apart as heavy manufacturing and online retail, with the same ending.
How mini-mills won and then lost the profit
For decades integrated steel mills dominated production. They started from iron ore, required enormous facilities, and carried heavy fixed costs. Then mini-mills arrived with a different process: melt scrap steel instead of smelting ore, in a smaller plant, at meaningfully lower cost in categories like rebar.
That cost advantage was real and it paid. Mini-mills entered the segments where the gap was widest, prices settled near the cost of the higher-cost integrated mills, and the newcomers earned genuine economic profit for years. The innovation worked exactly as intended.
It did not end there. More mini-mills entered, capacity grew, and eventually the market no longer needed the integrated mills to meet demand at all. They exited those segments. With the high-cost producers gone, price fell again — this time toward the cost of the highest-cost remaining mini-mill. The extraordinary profit disappeared.
Nobody was outmanaged. The advantage created profit and the entry it attracted erased it, which is what happens when enough firms share similar costs and sell an indistinguishable product.
The online version runs faster and looks different enough that people do not recognize it. You find a product, build a storefront, advertise well, and sales begin. Margins are healthy at first because few competitors are visible and the platform rewards early traction. Then other sellers notice, source from the same supplier, run similar ads, and the platform sorts everyone by price and reviews. Each entrant takes a little more of the margin.2
The steel version took thirty years. The drop-shipping version can take thirty weeks. The structure is identical, and in both cases the difference between early profit and durable profit was never effort.
That is what makes easy entry treacherous rather than convenient. The same low barrier that let you start lets everyone else start, and the more visible and attractive the opportunity, the faster it happens. Before entering a market, the useful question is not whether you can generate revenue. It is what happens to your margin when other people see what you see.
Only Structure Changes the Outcome
Notice what did not save anyone in either story. Strong demand did not. Large scale did not. Competence did not, and neither did working harder than the competition, because everyone in a price war is working hard.
If undifferentiated price competition drives margin to zero, only two things change the result, and both of them are structural.
The first is a genuinely lower cost than your rivals — not better purchasing or tighter operations, but a cost structure they cannot copy, which lets you stay profitable at prices that ruin them. That is what the mini-mills had, and the story shows both what it earns and how long it lasts once imitators arrive.
The second is differentiation that actually changes behavior: enough perceived difference that a one-dollar gap no longer moves the whole market. This is the more common route and the more commonly overstated one, because every founder believes their product is different and customers are the only ones whose opinion counts.
Both work by changing the parameters of the profit function rather than by trying harder inside it. Without one of them, feasibility is resting on branding language and execution optimism, and price competition will find that out.
Ask yourself — what happens when they see what you see?
Write down what you would charge and what you expect to earn on a unit. That is the number you have been carrying.
Now assume a competent, well-funded competitor enters next year selling something a customer would call the same thing. Not a bad competitor. A good one.
Do not model it. Just answer two questions. What price do you end up at, and what is your contribution then?
If the answer is that your price holds because customers would not switch, name the specific reason they would not, and be honest about whether it is a reason they would give or a reason you would give on their behalf. If the answer is that your price falls to something near your cost, you have learned the most important thing in this chapter, and you have learned it before committing anything.
The move: Evaluate profit at the price that survives competition, not the price you would prefer. If your margin only exists while rivals stay passive, you are holding a temporary condition rather than a business.
Most markets are not this harsh. Customers do notice differences, and they weigh brand, convenience, trust, timing, and service alongside price. Where those differences are real, a small price gap no longer redirects everything, and contribution can survive rivalry instead of collapsing to nothing. What that survival depends on, and how much of it you actually have, is the next question.
This argument is old and it is not mine. Joseph Bertrand made it in 1883, reviewing Cournot, and the model of price competition that follows from it carries his name (Bertrand 1883). The next chapter is the version where products differ.↩︎
Measured, and the numbers are stark. Across four million daily price observations for more than a thousand consumer electronics products on a price-comparison site, Baye et al. (2004) found that the gap between the two lowest prices averaged 23 per cent where only two sellers listed, and 3.5 per cent where seventeen did. The overall spread across all sellers did not collapse — prices were not converging to one price — but the competition at the front of the queue tightened sharply as the queue lengthened. That front is where the customers are. Orders keep coming and contribution keeps shrinking.↩︎